
Trim Tax

SR&ED Tax Credits — Turn Your R&D Spending Into Cash

Trim Tax identifies eligible projects, documents the technical work and prepares your T661 claim so your business receives the refundable credits it has earned — and keeps them through a CRA review.

Person reviewing a tax credits claim form at a desk

Most eligible businesses never claim

The Scientific Research and Experimental Development program is Canada's largest business incentive, worth billions of dollars each year, yet many software, manufacturing, engineering, food-processing and agriculture companies leave credits unclaimed because they assume their work is not "research." SR&ED is about technological uncertainty and systematic investigation, not laboratories or white coats.

If your team attempted to achieve a technological advancement, faced uncertainty that could not be resolved with standard practice, and worked through it systematically — building prototypes, running tests, iterating on designs — you may qualify for federal investment tax credits of up to 35% of eligible expenditures (for CCPCs, refundable in cash) plus provincial credits such as the Ontario Innovation Tax Credit.

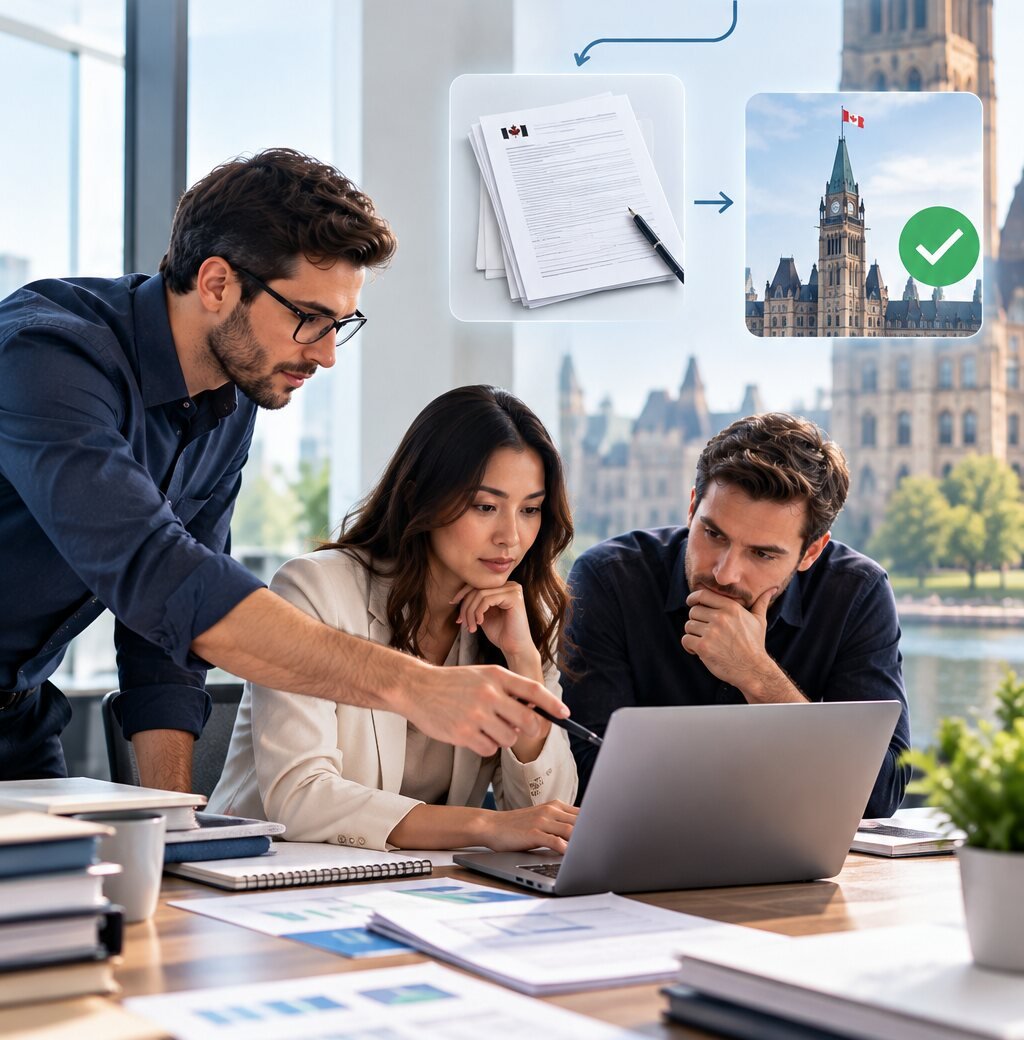
Team reviewing an SR&ED claim on a laptop beside a workflow from research to CRA approval

A claim that survives review

A SR&ED claim has two halves: a technical narrative for each project that answers the CRA's questions about advancement, uncertainty and systematic investigation, and a financial schedule that ties eligible salaries, materials, contractors and overhead to those projects.

Claims fail when the narrative describes a product instead of the technology problem, or when the costs cannot be traced to the work described. Trim Tax's technical and financial reviewers interview your engineers and developers, write narratives in the CRA's language, compile costs from your payroll and ledger, and file the T661 with your T2 — then defend the claim if the CRA selects it for review.

shape
shape
  • Eligibility assessment at no cost — we tell you honestly whether a claim is worth pursuing before you spend anything
  • Project identification and technical interviews with your engineers, developers and production staff
  • Technical narratives written to the CRA's criteria: technological uncertainty, hypothesis, systematic investigation and advancement
  • Cost identification: salaries and wages, materials consumed or transformed, contractor payments, third-party payments and overhead under the proxy or traditional method
  • Form T661, Schedule 31 (investment tax credit) and provincial schedules (Ontario Schedule 566 and others) prepared and filed with the T2
  • Integration with your corporate tax return so credits, refunds and carry-forwards flow correctly
  • Contemporaneous documentation systems — time tracking, project logs, test records — so next year's claim is stronger and easier
  • CRA review and audit defence, including preparation for and attendance at technical and financial reviewer meetings
  • Claims for prior years within the 18-month filing window
  • Coordination with other programs: IRAP, Ontario and federal grants, and digital media tax credits, to avoid double-counting

Industries we support

h1-feature-blur-shape
tt-code

Software, SaaS, artificial intelligence, machine learning and app development

Book a consultation
h1-feature-blur-shape
tt-gear

Manufacturing, machining, automation and process improvement

Book a consultation
h1-feature-blur-shape
tt-compass

Engineering, cleantech, construction technology and building products

Book a consultation
h1-feature-blur-shape
tt-leaf

Food processing, agriculture, beverages and packaging

Book a consultation
h1-feature-blur-shape
tt-medical

Medical devices, health technology and life sciences

Book a consultation
h1-feature-blur-shape
tt-chip

Electronics, hardware and IoT

Book a consultation

Why choose Trim Tax for SR&ED

  • Technical and financial expertise in one team: engineers who understand your work and CPAs who tie the costs to the T2.
  • Honest eligibility calls — we decline projects that will not qualify rather than filing claims that invite review.
  • Narratives written for the CRA's reviewers, not marketing copy.
  • Full review defence included, by the same people who prepared the claim.
  • Flexible pricing: a fixed fee or a contingency percentage agreed in writing before work starts.
  • Integrated corporate tax, so the credit, the refund and the carry-forward are handled without a second accountant.

Frequently asked questions

Experimental development, applied research or basic research undertaken to achieve a technological advancement, where there was technological uncertainty that could not be resolved with standard practice, and the work was carried out through systematic investigation. Routine engineering, quality control, market research, style changes and commercial production do not qualify, but support work directly related to eligible projects does.
Canadian-controlled private corporations can receive a refundable federal credit of 35% on the first $3 million of qualifying expenditures each year (subject to taxable capital limits), with provincial credits — such as Ontario's 8% Innovation Tax Credit — on top. Other corporations, individuals and partnerships receive a 15% non-refundable federal credit.
Yes. Claims must be filed within 18 months of the end of the fiscal year in which the expenditures were incurred. The deadline is not extendable, so a corporation with a December 2025 year-end must file its 2025 claim by June 2027.
SR&ED claims are reviewed on their own track by SR&ED technical and financial reviewers, separate from a general corporate audit. A well-documented claim with a clear narrative rarely causes problems; we defend every claim we prepare.
The CRA expects contemporaneous evidence — commit logs, test results, design iterations, meeting notes, time records. Claims can be supported by reconstruction, but contemporaneous records are far stronger, which is why we set up simple systems for future years.
Yes, but government assistance such as IRAP reduces the eligible expenditure pool. We calculate the net claim and coordinate with any other credits you receive.

Find out if your work qualifies.

Book a free SR&ED eligibility call — call 647 243-5076 or email info@trimtax.ca.

Office: 400 Applewood Cres., Suite 100, Vaughan, ON L4K 0C3
Hours: Monday to Friday, 9:00 am to 6:00 pm ET

    Fields marked * are required.

    Get plain-language tax updates from our CPAs.

      No spam. Unsubscribe anytime.

      shape
      shape

      © 2026 Trim Tax. All rights reserved.

      Trim Tax is an independent accounting firm and is not affiliated with the Canada Revenue Agency or any government agency. Information on this website is general in nature and does not constitute professional advice. Outcomes depend on individual circumstances.