
Final Returns, Estate and Trust Filings — Handled With Care
Executors and trustees rely on Trim Tax to prepare final returns, estate T3s and clearance certificates correctly, so the estate can be settled without CRA delays or personal liability.
Support for executors, trustees and families
Settling an estate means dealing with the CRA at a difficult time. The deceased's final T1 must report income to the date of death and the deemed disposition of capital property; optional returns can reduce the overall tax; the estate itself becomes a trust that files T3 returns until it is wound up; and the clearance certificate that protects the executor from personal liability cannot be requested until everything else is done.
Each step has rules and deadlines, and mistakes fall on the executor personally. Trim Tax handles the full sequence, coordinates with the estate lawyer, and explains each step in plain language.
Trusts now have annual filing obligations
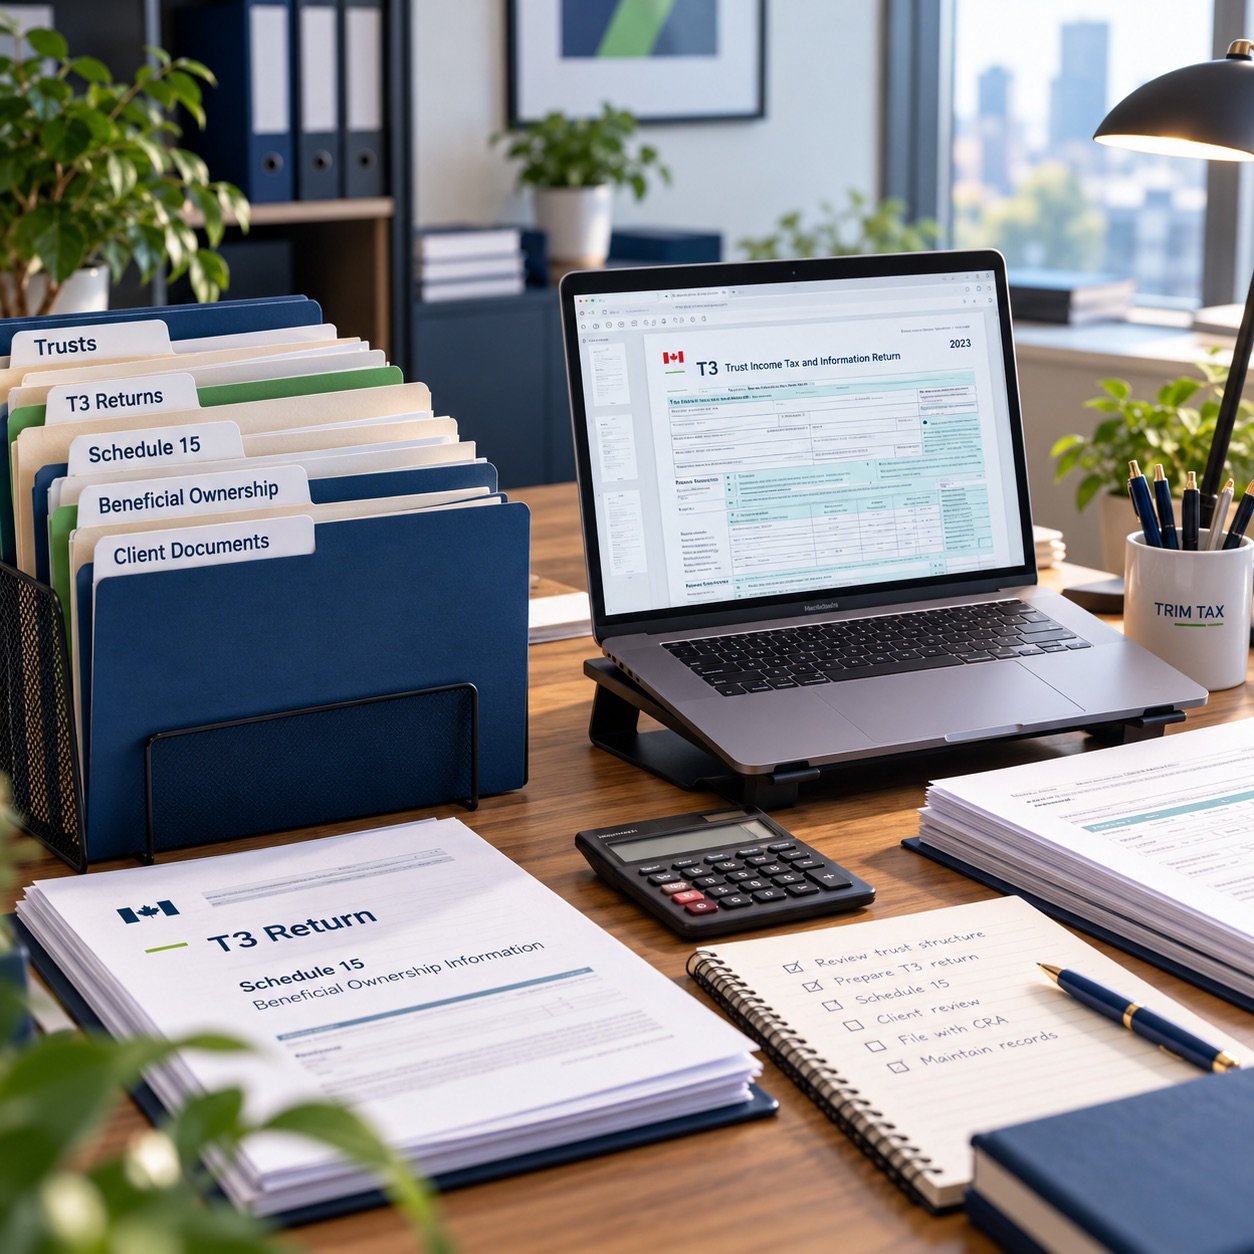
Since the 2023 taxation year, most express trusts — family trusts, alter-ego and joint partner trusts, testamentary trusts and many bare trust arrangements — must file an annual T3 return with Schedule 15 beneficial ownership information, even when they have no income and would not previously have filed.
Penalties for non-filing are significant. Trim Tax reviews whether your trust is affected, prepares the returns and maintains the beneficial ownership schedule year to year.


Estate and trust services
- Final T1 return for the year of death, including deemed disposition of capital property, RRSP/RRIF inclusion and rollover elections to a spouse
- Optional returns (rights or things, business income, testamentary trust income) to reduce overall tax
- Prior-year returns for a deceased person who was behind on filing
- Graduated Rate Estate designation and estate T3 returns for up to 36 months at graduated rates
- Family trust, alter-ego, joint partner and testamentary trust annual T3 filings with Schedule 15 beneficial ownership reporting
- Trust income allocation and T3 slips to beneficiaries; 21-year deemed disposition planning
- Clearance certificate applications (TX19 and TX21) before final distribution
- Estate accounting for passing of accounts and beneficiary reporting
- Probate planning, estate freezes and post-mortem planning (pipeline and subsection 164(6) loss carry-back) with legal counsel
- Bankruptcy pre- and post-bankruptcy returns coordinated with the licensed insolvency trustee
- Estates with foreign assets or non-resident beneficiaries: Canadian reporting, Part XIII withholding and NR4 slips on distributions, coordinated with foreign advisors
- Donation planning on death and charitable bequests
Who we help
Executors and estate trustees, including first-time executors
Book a consultation
Trustees of family, alter-ego and testamentary trusts
Book a consultation
Families settling a parent's or spouse's affairs
Book a consultation
Estate lawyers who need a CPA partner for the tax filings
Book a consultation
Individuals planning their own estate with a will, trust or freeze
Book a consultation
Trustees in bankruptcy and individuals filing pre- and post-bankruptcy returns
Book a consultationWhy choose Trim Tax for estate and trust work
- CPAs who prepare final returns and T3s throughout the year, not just at tax time.
- Executor protection first: nothing is distributed before the returns are filed and the clearance certificate is requested.
- Optional-return and rollover analysis that routinely reduces the tax on death.
- Trust reporting handled proactively under the new Schedule 15 rules.
- Coordination with your estate lawyer and, where needed, your insolvency trustee.
- Compassionate, plain-language communication with families, and fixed fees quoted in advance.
Frequently asked questions
Let us handle the CRA so you can focus on your family.
Book a confidential consultation — call 647 243-5076 or email info@trimtax.ca.
